What is the scope and industry significance of the Heat Treated Steel Plates Market?
The Heat Treated Steel Plates Market serves as the backbone of global heavy industry, encompassing plates processed via annealing, tempering, normalizing, and quenching. Our research defines its scope as essential high-strength metallurgical components utilized in extreme environments. Given its critical role in infrastructure, this market acts as a barometer for industrial capital expenditure across major economies.
Structural Growth Drivers and Market Constraints
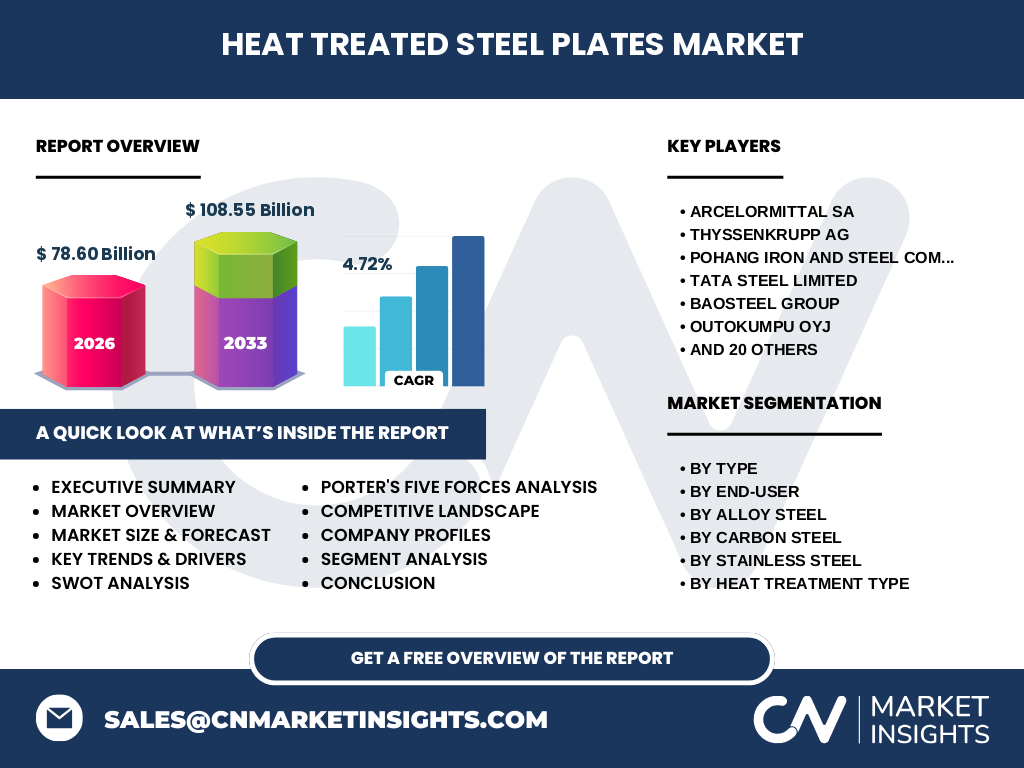
Our analysis indicates that infrastructure modernization and the energy transition are the primary catalysts. The market faces a valuation hurdle of 78.60 Billion in 2026, pressured by volatile raw material costs for iron ore and ferro-alloys. Logistical bottlenecks at key ports and stringent emission mandates from bodies like the International Energy Agency create localized constraints for traditional carbon-intensive production facilities.
Emerging Trends in High-Performance Steel
A pivot toward sustainable metallurgy is the defining trend. Leading innovators like ArcelorMittal SA and Voestalpine AG are prioritizing green hydrogen-based steelmaking. Furthermore, the rising demand for high-alloy stainless steel in corrosive offshore applications is shifting the product mix. This trend favors integrated players with proprietary heat treatment technology that can meet increasingly rigorous ISO safety standards for deep-sea environments.
Impact of the Global Pandemic on Production Trajectories
The COVID-19 pandemic induced a temporary paralysis in supply chains, particularly impacting automotive demand. Recovery has been uneven, categorized by strategic destocking followed by a rapid rebound in offshore wind projects. Industry giants like Nippon Steel had to recalibrate production capacities as regional logistical disruptions forced a localization of supply, significantly altering the long-term CAGR outlook for the Heat Treated Steel Plates Market.
Competitive Benchmarking and Market Dynamics
The landscape remains highly fragmented, featuring consolidated titans such as Baosteel Group, Tata Steel, and POSCO. Competitive advantage is currently derived from vertical integration—securing raw material sourcing—and R&D dominance in metallurgical stability. Companies like Tenaris SA and Outokumpu Oyj emphasize specialized niche segments, while larger entities prioritize economies of scale to buffer against fluctuating steel plate demand.
Executive Summary: 2027-2033 Market Outlook
The Heat Treated Steel Plates Market is poised for sustained expansion, with total market size projected to reach 108.55 Billion by 2033. Our research reflects a steady CAGR of 4.72%, driven by intensified urbanization and heavy machinery deployment. Investment success in this sector requires navigating the transition from carbon-heavy reliance toward high-strength, low-alloy steel innovations tailored for renewable energy infrastructure.
Market Forecast and Valuation Trajectory
From 2027 to 2033, we forecast consistent growth as the market value climbs from its current trajectory toward the 108.55 Billion target. This growth is contingent upon geographic diversification in the Asia-Pacific region and the electrification of industrial power plants, which requires advanced heat-treated components to endure extreme thermal cycling, thus bolstering demand for high-performance Martensitic Stainless steel and related metallurgical grades.
Segmentation Analysis of the Steel Plate Ecosystem
Our analysis segments the market into three core pillars: Carbon Steel (the volume leader), Alloy Steel (the innovation driver), and Stainless Steel (the performance specialist). Each category serves distinct end-users, from Automotive and Heavy Machinery to Off-shore structures. By dissecting these, we identify how different heat treatments—such as quenching for hardened plates—add distinct value-added properties required by specific industrial sectors.
Geographic Performance and Regional Dynamics
Regional performance is dominated by the Asia-Pacific hub, where industrial output in China and India anchors global demand. Our research highlights that while North America and Europe focus on high-tech alloy production, the sheer volume of carbon steel plates remains the highest in emerging economies, influenced by localized building and construction booms and massive infrastructure pipeline approvals.
In-depth Regional Review: Asia-Pacific and Beyond
The Asia-Pacific region functions as the global industrial engine, with companies like Jiangsu Shagang and Ansteel Group optimizing local logistics to keep prices competitive. Conversely, the European market is defined by regulatory compliance and the adoption of carbon border adjustment mechanisms, compelling players like Salzgitter AG to optimize heat treatment energy efficiencies to remain viable against cheaper imported steel alternatives.
Strategic Positioning of Leading Global Participants
Market leaders define their roles through specialization. Nippon Steel Corporation remains a powerhouse for automotive grades, while Gerdau SA leverages regional strength in the Americas. Allegheny Technologies Inc. excels in high-margin, specialized stainless steel segments. This competitive mix demonstrates that Heat Treated Steel Plates Market participants thrive by balancing mass-market carbon steel capabilities with advanced high-alloy metallurgical R&D.
Porter's Five Forces Analysis
The market demonstrates moderate supplier power due to iron ore concentration, but high competitive rivalry among established groups like US Steel Corp and Hyundai Steel. The threat of substitution from composites is high in lightweight segments, while barriers to entry remain elevated due to the massive capital investment required for heat treatment facilities and global distribution networks.
SWOT Analysis: Navigating Industrial Challenges
Strengths include vast production footprints and deep material expertise. Weaknesses persist in legacy, energy-intensive infrastructures. Opportunities exist in the green energy sector, specifically wind towers requiring high-tensile plates. Threats comprise unpredictable regulatory interventions on trade and potential supply chain disruptions, necessitating that firms like Wuhan Iron and Steel adopt more agile, data-driven production scheduling and diversified supply chain ecosystems.
Value Chain Analysis: From Raw Materials to End-Users
The value chain originates with iron ore extraction and coking coal supply. Processing through electric arc furnaces and heat treatment cycles constitutes the mid-stream, where primary value is added. The final distribution connects major ports to shipbuilding yards and construction sites. Our research indicates that profitability is optimized at the heat treatment stage, where metallurgical precision dictates the final performance of the plate.
Investment Insights and High-Potential Areas
Investors should prioritize companies integrating digital thermal monitoring into their heat treatment processes, as precision correlates with higher margins. The Energy and Power sector represents the most attractive segment for long-term growth, specifically regarding plates for offshore wind turbines. Identifying mid-tier producers in emerging regions who are transitioning to high-value Alloy Steel production offers significant upside potential compared to saturated carbon steel markets.
Conclusion and Strategic Key Takeaways
The Heat Treated Steel Plates Market is evolving toward higher performance and lower carbon footprints. With a forecasted expansion to 108.55 Billion, success belongs to firms that master metallurgical agility. Stakeholders must emphasize decarbonization technology and supply chain resilience. Navigating this 4.72% CAGR environment requires a dual focus on regional volume dominance and niche innovation within the alloy steel segments.
Methodological Framework for Market Estimation
Our research methodology involves data triangulation: integrating primary interviews with C-suite executives in the steel sector, exhaustive analysis of trade registry data, and macroeconomic indicators. We cross-reference production capacity reports from national steel associations against customs clearance data to estimate the market size of 78.60 Billion. This ensures a rigorous, evidence-based foundation for all financial projections and strategic insights provided.
Scope of the Report and Analytical Coverage
This report examines the global Heat Treated Steel Plates Market, covering key segments: Carbon, Alloy, and Stainless Steel across all major heat treatment processes. The geographical scope spans North America, Europe, APAC, and RoW. Limitations include exogenous factors like geopolitical trade tariffs, which are addressed as variables in our predictive modeling to ensure the highest analytical accuracy for our stakeholders.
Recent Developments and Market Announcements
Significant recent developments include strategic mergers aimed at consolidating production for renewable energy demand. Partnerships between Nippon Steel and local hydrogen producers demonstrate a shift toward decarbonized processing. Furthermore, product launches focusing on ultra-high-strength steel plates for naval construction indicate that firms are aggressively pursuing the shipbuilding and off-shore infrastructure segments, directly targeting the high-growth trajectory leading into 2033.